How to Secure Flexible Business Loans for Your Startup
Understanding Flexible Business Loans
Starting a business requires not only a great idea but also the capital to bring it to life. Flexible business loans can be a game-changer for startups, offering the financial support needed to manage cash flow and invest in growth. These loans provide adaptable repayment terms and conditions, making them an attractive option for entrepreneurs.
Unlike traditional loans, flexible business loans allow you to adjust the repayment schedule based on your business’s cash flow. This adaptability can help you manage your finances better, especially during the early stages of your startup.
Types of Flexible Business Loans
There are several types of flexible business loans available, each catering to different needs. Some of the most popular options include:
- Line of Credit: This allows you to borrow up to a certain limit, and you only pay interest on the amount you use.
- Invoice Financing: This allows you to borrow money against your outstanding invoices to improve cash flow.
- Merchant Cash Advances: This provides a lump sum of cash in exchange for a percentage of future sales.
Understanding these options can help you choose the right type of loan that aligns with your business goals.
Preparing for a Loan Application
Before applying for a flexible business loan, it’s essential to prepare thoroughly. Lenders will look at several factors to determine your eligibility. Here are some steps to ensure you are ready:
- Assess Your Credit Score: A good credit score increases your chances of approval. Check your score and make improvements if necessary.
- Create a Solid Business Plan: A detailed business plan demonstrates your preparedness and potential for success.
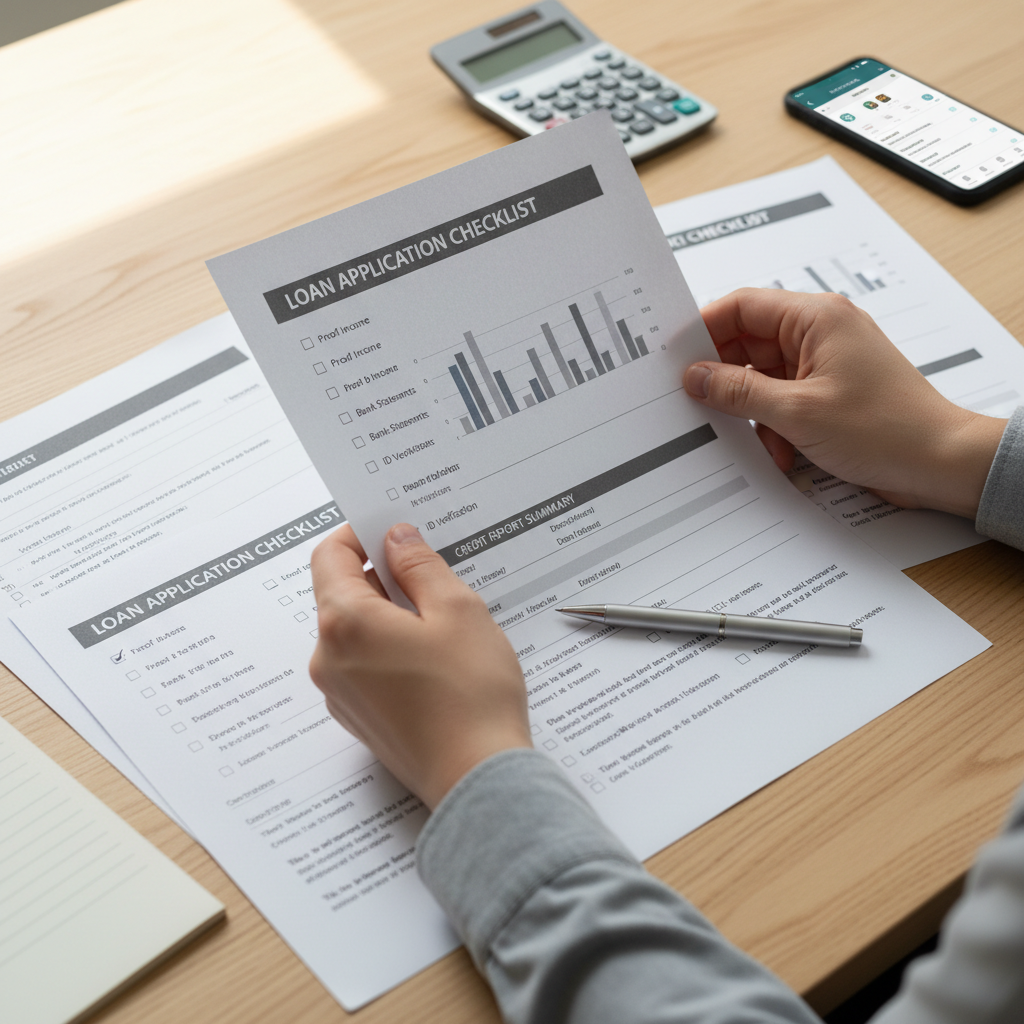
- Gather Financial Documents: Prepare financial statements, tax returns, and other relevant documents to support your application.
Finding the Right Lender
Choosing the right lender is crucial for securing a flexible business loan. Research potential lenders, compare their terms, and read reviews from other entrepreneurs. Consider reaching out to local banks, online lenders, and credit unions to explore your options.
Additionally, consider working with a financial advisor who can help you navigate the lending landscape and find the best loan terms for your startup.
Negotiating Loan Terms
Once you’ve found a lender, the next step is negotiating loan terms. Be clear about your needs and financial situation. Discuss interest rates, repayment schedules, and any fees associated with the loan. Remember, the goal is to secure terms that support your business’s growth and sustainability.
Securing a flexible business loan can be a pivotal step in your startup journey. By understanding your options and preparing thoroughly, you can find a loan that not only meets your current financial needs but also supports your long-term business goals.